 The bimonthly news publication for aviation professionals.
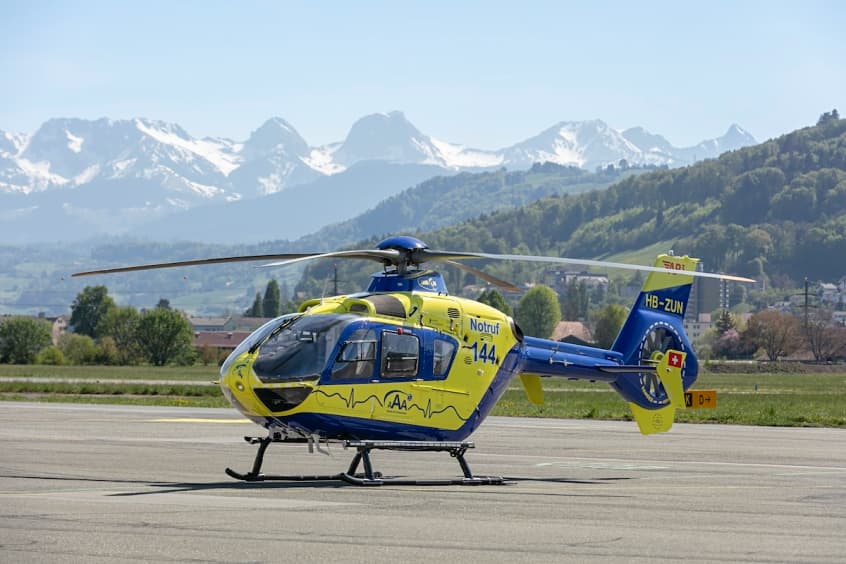
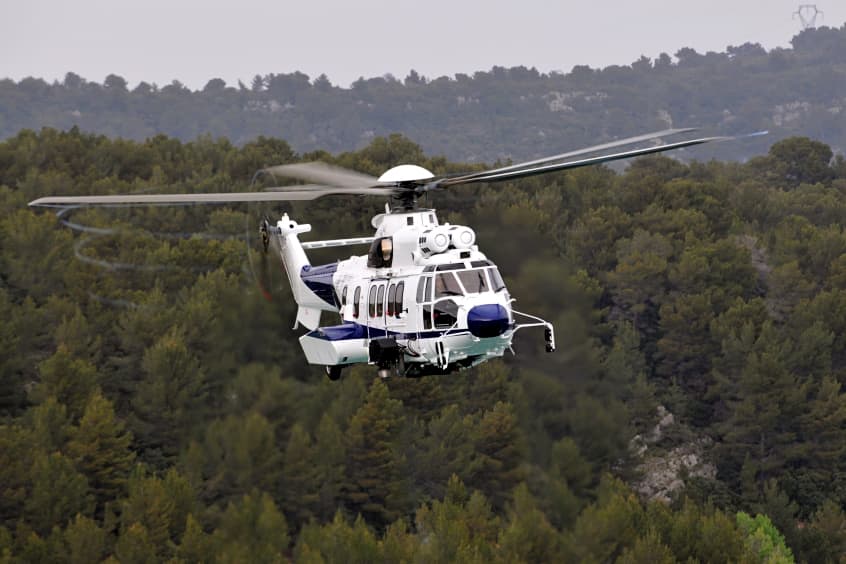
Retail sales in the preowned twin-engine helicopter market rose 8% year-on-year in the first half of 2026, while supply for sale fell 33% to its lowest level in five years, according to Aero Asset's 2026 Half Year Heli Market Trends Twin-Engine Edition.
The tighter inventory environment pulled the overall absorption rate down from 18 months a year ago to 11 months. Pricing continued to strengthen over the period, with overall median transaction prices up 6% year-on-year. Heavy twin median transaction pricing reached a five-year high, while the light and medium segments posted mixed results. Retail activity diverged across the three asset classes: medium and heavy twin markets recorded stronger sales, while light twin activity softened. Supply tightened across all three categories, with light and medium twin inventory both reaching five-year lows.
“While transaction activity increased during the first half of the year, the most significant development was the continued contraction in supply for sale,” says Valérie Pereira, vice president of market research at Aero Asset. “Supply reached a five-year low while pricing continues to strengthen, creating a favourable environment for sellers. The improvement in absorption rate reflects a balanced market.”
North America remained the largest retail transaction market, accounting for 46% of global transactions, while Europe recorded the strongest growth in retail sales, up 75% year-on-year, and held the largest concentration of available supply.
The report, available to download from Aero Asset's website, includes a conversation with Steve Borrowdale, managing director and accountable manager of Multiflight.